


On-Chain Tape: Friday Printed $128 of Market Value For Every Dollar Anyone Committed
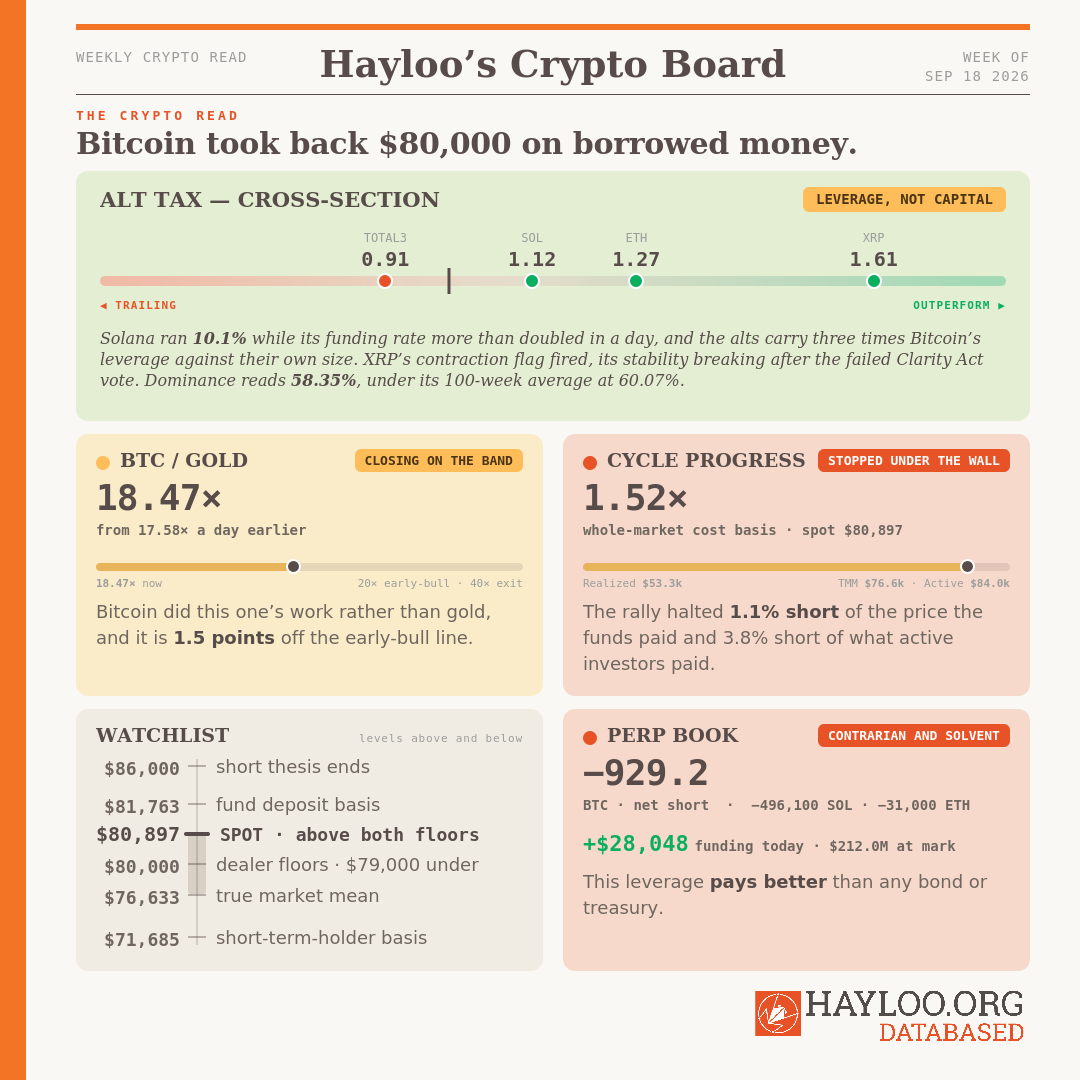
Bitcoin added $91.9 billion of market value on Friday. The capital newly committed to the chain in the same session was $716 million. That is $128 of market capitalisation for every dollar that actually went in, and it is the whole story of this bulltrap. Across seven days the chain’s cost base grew 0.083% while price rose 4.78%. Leverage took Bitcoin from $75,590 on Tuesday to $80,896.90 on Friday, not people buying coins and keeping them.
Notional open interest grew 7.8% on the day against a 1.8% rise in the contract count, so the only size that arrived was borrowed money. Funding rose as price rose, Bitcoin to 7.7% annualised and Solana to 10.9% after more than doubling in a session, which is longs paying a ridiculous prime to hold a bulltrap that’s going to be short-lived. One-week realised volatility went from 26.8 to 37.4 and now sits above implied volatility at 35.46. A move that outruns its own options market is a liquidation mechanic, just wait for it.
Holders sold into this pump like hotcakes. By dollar weight the realised profit-and-loss ratio printed 3.35, a local top-signal in our own book. The long-term holders were not among the ones taking profit: they realised $322.7 million of losses, 1.58 times their own 30-day pace, on a session Bitcoin rose 5.9%.
Where the rally stopped matters as much as how far it ran. Price halted at $80,897, underneath the fund deposit basis at $81,763 and the active-investor mean at $84,001. Those are the two cohorts that need higher prices to get whole, and both are running for the hills. Supply in profit jumped 7.4 points in one session to 71.7%, which means 7.4% of every coin in existence has its cost basis inside the $4,526 band the price just crossed. That is the densest block of overhead supply on the chain and it now sits at breakeven. We are not the only fund selling into this strength. Holders are getting their money back with little motivation to hold Bitcoin any longer.
The venue and fund data say the same thing more quietly. The seven-day fund sum is still $440.1 million negative even after Thursday’s $159.5 million inflow. Coinbase sold $282.8 million net across the seven days to Friday. Binance bought $335.9 million over the same window, which is the one genuine change on the demand side and the reason to watch this rather than dismiss it. Exchange balances fell by 329 coins, which is noise. Speculative capital in motion rose 29.4% to $38.8 billion, and that is the signature of coins moving into short-term leveraged hands rather than new money arriving to pump Bitcoin into Valhalla.
So the question for next week is whether realised capital starts growing, ahead of where the price goes. Longs are paying 7.7% and 10.9% annualised to carry positions that no committed capital has shown up to support. Either buyers arrive and the cost base begins rising, which is the invalidation we wrote down and will honour, or the funding bill comes due on the people carrying it.
🔴 $128 of market value per dollar committed, holders selling at 3.35 times their loss-taking, and the rally stopped short of every cohort that needs to sell.
Majors On-Chain: Everything Rallied, Every Chain Lost Money
The four major altcoins put in 3% to 11% weeks. Three of the four lost capital over those seven days and the fourth barely registered. Ether shed 0.28%, XRP 0.50%, Doge 0.29%, and Solana added 0.02%. Bitcoin added 0.08%. Every one of these rallies was financed by leverage rather than by buyers.
Ethereum. Closed at $2,610.06, up 3.8% on the week and 15.6% above the market’s average cost of $2,257.59. Its movers remain the best-behaved in the set, a realised profit-and-loss ratio of 4.43 and a spent-output ratio of 1.02 with 55.4% of supply in profit, and its cost base still shrank 0.28%, the largest outflow of the majors we track. It carries 7.6% of its own supply in open futures against Bitcoin’s 2.4%, which is how a chain moves 6.7% in a day on money leaving the chain. Our Ethereum short sits at $2,600 and the close is 0.4% above it. We will be sleeping well tonight.
Solana. Rose 10.1% to $112.69, the strongest of the four and more than double Bitcoin’s move, on funding that went from 0.013% to 0.030% a day. The holders who bought at $116.27, the chain’s average cost, are now 3.1% under water. Solana’s cost base grew 0.02%, so nearly all of that 10% came from borrowed money paying an escalating rate. We are short 496,100 coins at $93.42.
XRP. Closed at $1.3965, up 3.0%, still 4.8% below the $1.4664 its holders paid on average, with 45.8% of supply in profit. Its cost base shrank 0.50%, the worst of the four, and open futures are the lightest in the set at 1.4% of derived value. A coin that rallies on the least leverage available and still bleeds capital is a coin nobody is accumulating. We sold 46.1 million coins above $1.40 this week and we’re glad they are gone.
Doge. Rose 3.8% to $0.0874 and remains 25.8% below the $0.1178 its holders paid. Only 22.6% of supply is in profit, its movers sold at a loss harder than anything else in the set at a realised profit-and-loss ratio of 0.02, and its cost base shrank 0.29% while its open futures stayed the heaviest at 7.4% of derived value. That is the exact combination that produces a 7% day, before giving it all back.
🔴 Three of the four lost capital in the week they rallied, and every one of those rallies was bought with borrowed money.
— Capital Flow Analyst (Priya Sandoval) · Fundamental Research Analyst (Charlotte Donovan)
Hayloo’s Perp Book
Size and direction. Net short Bitcoin, Solana, and Ethereum. Bitcoin: 929.2 coins short from a blended $79,139.80, the leg doubled to full size this week. Solana: 496,100 coins short from $93.42, unchanged, and Ethereum: 31,000 coins short from $2,600. All three legs are notional $212.0 million short.
Funding rate carry. All legs are receiving. Today’s print is $28,048 and the seven-day mean is $16,645 a day on current notionals, which annualises to $6.08 million. We are being paid by the same leverage that cost us patience, which is the trade working the way we like.
Position versus thesis. We doubled the Bitcoin short into the pump, and the reason is realised capital growth at 0.083%. No invalidation has fired: $86,000 on a completed weekly close is 6.3% away, and the last completed close reads $76,819.
What has changed is that our cushion is now our trapdoor. The true market mean at $76,633, the 20-day line at $78,143, maximum pain at $78,000 and the dealer floors at $80,000 and $79,000 all sit beneath the price.
On the spot side the selling is all but done. We sold 39.1 million XRP on September 14 at $1.456 and, on September 15, 400 Bitcoin at $78,208, 238,000 Solana at $102.60 and 7 million XRP at $1.425. Friday overtook two of the four: Bitcoin trades 3.4% above the $78,208 fill and Solana 9.8% above the $102.60 fill. The XRP fills still sit 2.1% and 4.3% above the mark. What is left is 100 Bitcoin, worth $8.09 million at the close, and 10 million XRP.
The XRP plan was to sell into a Clarity Act pass. There was no pass: cloture failed 49 to 50 on September 15, eleven votes short of sixty, XRP fell 10% to $1.30 with about $571 million of long futures liquidated, and two days later the Securities and Exchange Commission (SEC) issued a five-year blanket exemption for venues listing tokenised securities. The agency did in one letter what the Senate could not do in a year, and it did it with a clock attached. Rules written that way can be unwritten the same way. We sold 46.1 million coins at $1.43 to $1.46 into a catalyst that never arrived, and the average price every XRP holder has paid now sits at $1.4664, above our sell line.
— Lead Trader (Jordi Federer)
Forward Thesis
We expect this to resolve downward over four to twelve weeks. Our case did not weaken this week. A rally that prints $128 of market value per dollar committed, on rising funding, into the densest overhead supply on the chain, is the mechanism our short thesis describes rather than the one that refutes it.
The first rung on the downside is the short-term-holder basis at $71,685, 11.4% below spot, with the 2026-cohort basis at $71,347 marking the same shelf. Between here and there sit the 7.4% of supply that crossed into profit in a single session and that crosses back out of it on a $4,500 retrace, which is the trapdoor under this price. The realized price at $53,270 is the named rung far below, 34.2% down, where the support test for a market bottom lives.
What changes our mind, each against its current value.
Michael Howell’s next liquidity print with the three-month rate positive, the level rising with it, and the annual leg turning up. Now +1.2% from −0.3%, with the level down a second consecutive week and the annual leg at −0.1%. Untouched by this week’s crypto tape.
A completed weekly close above $80,000 with Coinbase and Binance both net buying on the same window. The price limb is live for the first time, the running week marking $80,897 against a last completed close of $76,819. The demand limb is half-met: Binance bought $335.9 million, Coinbase sold $282.8 million. Sunday’s close settles the first half.
A completed weekly close at or above $86,000, which ends this short thesis outright and needs nothing else with it. Spot is 6.3% below it, against 12.6% a day ago.
Two daily closes above the active market’s mean at $76,633 with realised capital growing more than half a percent on the week. Friday is the first such close and realised capital grew 0.083%. This is the test holding the thesis together, and it is holding on the money limb rather than the price limb.
On our use of AI:
We’re a private crypto fund out of Switzerland. We built a Neurosymbolic Compound AI System for our own desk: it follows our strategies, it reads the news that affect our portfolio, it sits on a database going back decades, and brings math to our everyday emotions. We call it Hayloo. It’s our best hire. This Substack is compiled by Hayloo a.
Humans have written machine-assisted for centuries. What never changes is who decides.
Nothing at Hayloo INC. was ever decided by a machine.
What we publish is what we defend as a team. When it’s wrong, it’s wrong because humans signed it.
Jordi Federer, Founder, Hayloo INC.
Watchlist
Realised capital, weekly. The one number that separates a funded advance from a leveraged one. It needs more than half a percent in a week to invalidate us. It has grown 0.083% in seven days.
Funding on Bitcoin and Solana. 7.7% and 10.9% annualised, both rising. Longs paying up to hold an unfunded rally is a cost with a clock on it; funding collapsing back to zero says the leverage has been cleared.
Bitcoin $80,000 and $79,000. The dealer hedging floors, 1.1% and 2.3% under spot, and the switch between cushion and accelerant.
Bitcoin $76,633 and $76,371. The active market’s mean and Thursday’s close. Back under both and the 7.4% of supply that just turned profitable turns loss-making again.
Bitcoin $86,000 on a completed weekly close. Our thesis ends there, 6.3% above spot. Our own line is $96,013.70, so the thesis is reached well before the account gets margin called.
The fund window. Seven-day sum still $440.1 million negative after Thursday’s $159.5 million inflow. Two weeks of both venues buying with that sum above $1.5 billion positive is the demand invalidation.
Solana $116.27. The average price Solana holders paid, 3.1% above spot. Through it and the chain’s entire under-water cohort is whole and free to sell.
Ether $2,600. Our own entry, 0.4% under the close.
The September 25 quarterly expiry. Max pain $78,000, 3.6% below spot, 429,745 contracts at a put-to-call ratio of 0.56, the call wall at $85,000 with a second at $90,000.
We’re short Ethereum with a target of $1.4K – Hayloo’s Altcoin Tax Week 38

The Beta Desk · Hayloo Unchained · week of 16 September 2026
The Team
Jordi Federer — Lead Trader. Owns the book and the publication. Sizing, staging, and every decision that moves capital.
Theodore Brennan — Chief Macro Strategist. Central-bank reaction functions, the dollar, and the rate path.
Julian Harlow — Global Liquidity Director. The liquidity engine, the collateral multiplier, and the transmission lag into price.
Margaux Lindqvist — Geopolitical Intelligence Officer. State behavior, escalation mechanics, and the tails that reprice commodities.
Marcus Vasquez — Hard Asset Strategist. Gold, the debasement basket, and the hard-money ratios.
Sienna Whitfield — Inflation & Real Asset Analyst. Energy, the inflation impulse, and the real-asset complex.
Priya Sandoval — Capital Flow Analyst. Fund flows, positioning, derivatives, and where the marginal dollar comes from.
Charlotte Donovan — Fundamental Research Analyst. On-chain cohorts, cost bases, and the structural read beneath the tape.
Lukas Marchetti — Technical Analyst. Market structure, moving-average regimes, and the levels that fire.
Disclaimer
The information is provided for information purposes only and on the basis that it will not be relied upon. No information contained herein constitutes a personal recommendation or investment advice.
The information (including any expressions of opinion or forecast) has been obtained from, or is based on, sources believed by the author to be reliable, but are not guaranteed as to their accuracy or completeness and should not be relied upon. The information is provided without obligation on the part of the author and on the understanding that any person who acts upon it or changes his investment position in reliance on it does so entirely at his own risk. The information does not constitute an offer to buy or sell or an invitation to make an offer to buy or sell any financial instrument.
Information is current only as at the date it is first posted and may no longer be true or complete when viewed by you. All information may be changed or amended without prior notice.
No representation, warranty or undertaking is given as to the accuracy or completeness of the information by the author and no liability is accepted by the author for the accuracy or completeness of such information. In no event will the author be liable to any person for any direct, indirect, special, or consequential damages arising out of any use of the information, including, without limitation, any lost profits.
You should be aware that the Internet is not a completely reliable transmission medium. The author does not accept any liability for any data transmission errors such as data loss or damage or alteration of any kind, including, but not limited to any direct, indirect or consequential damage, arising out of the use of the product or services referred to herein.
The materials provided here including text, photographs and other images, are protected by copyright and/or other intellectual property rights. All copyright (and any other intellectual property rights) in these materials is either owned by the author, or is used by the author under licence.