


Hayloo Unchained Trading Team—May 20, 2026
Contributors this week: Lead Trader, Chief Macro Strategist, Global Liquidity Director, Geopolitical Intelligence Officer, Hard Asset Strategist, Capital Flow Analyst, Fundamental Research Analyst.
Hayloo’s Macro Board
TL/DR
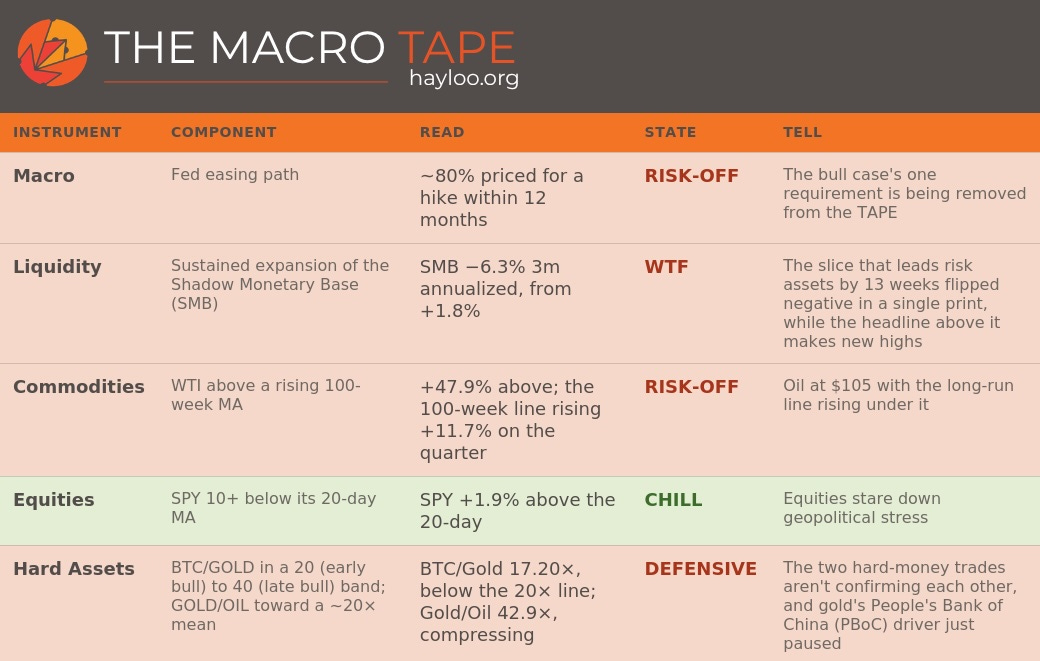
GEO stress: equities keep the gate. Oil is sustained 47.9% above a rising 100-week moving average (MA), and the capital-repatriation stack is dense. Yet artificial intelligence (AI)-driven equities are the only thing keeping confirmed geopolitical stress from cascading through the markets. Today’s Federal Open Market Committee (FOMC) minutes plus Nvidia earnings are the immediate event-risk window below it.
Hard assets: gold’s driver just paused. PBoC injections are turning lower. With that leg removed, the BTC/Gold ratio at 17.20× sits below the 20× early-bull line, and Gold/Oil at 42.9× is compressing toward its long-run mean through oil rising, not gold rising. The path the bull case modeled has changed even where the destination has not.
Headline up, engine down—the week’s defining divergence. Michael Howell’s aggregate Global Liquidity printed a new high at $192.4 trillion. The Shadow Monetary Base (SMB) underneath it—the granular slice that actually leads risk assets by about thirteen weeks—flipped from +1.8% to −6.3% three-month annualized in one print. The two have tracked each other for most of the cycle. This week they came apart. That’s the signal.
The on-chain structure turned defensive. Bitcoin reclaimed the True Market Mean (TMM) at $78,300 during the rally and lost it the same week; one push through is not a regime change. The Realized Profit and Loss Ratio (RPLR) sits at 1.8, below the 2.0 that would confirm a genuine buy-side recovery, and the dominant negative-gamma cluster has relocated to $75,000—just below spot—where dealer hedging now amplifies downside rather than dampening rallies.
The demand side is cooling. Spot Bitcoin exchange-traded funds (ETFs) logged their first weekly outflow in seven weeks, −1.039billion, andthecurrentweekisrunning−1.45 billion across three consecutive negative prints. Binance flows recovered modestly from deeply negative levels while Coinbase stayed subdued—the multi-channel positive of one week ago has lost its Coinbase leg.
Three central banks hardening into one energy shock. Markets price roughly 80% odds of a Fed hike this year, with the first cut now pushed to the second half of 2027. The European Central Bank (ECB) has a Governing Council member naming a June hike “quite likely” if the Iran war runs on, Iceland delivered its second hike of the conflict, and global long-ends sit at multi-decade and post-1999 highs. The bull case’s one requirement—a Fed easing path—is being removed in real time.
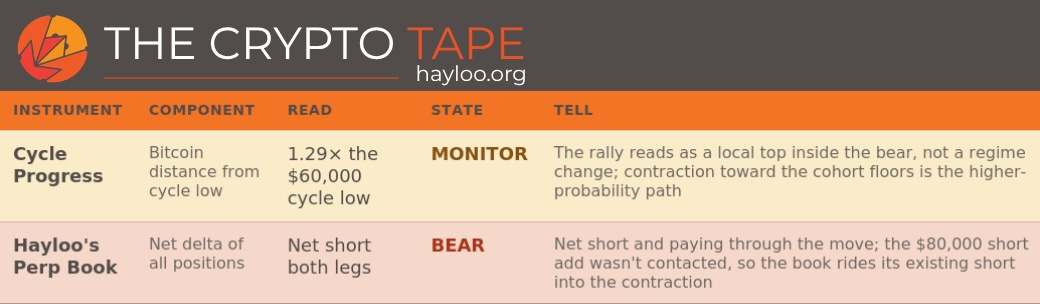
Forward thesis: contraction, not a turn. We read the next several weeks as a move toward the cohort floors—first $76,900, then $71,400—not a clean bottom at current levels. The $80,000 zone is the rejection band that already failed below it, not the next contact ahead. The book stays net short; if $76,900 breaks and the market traverses the $75,000 gamma band, the $66,000 long add becomes the next decision.
Hayloo’s Crypto Board
Tape of the Week
This week’s tell was a divergence. Michael Howell’s aggregate Global Liquidity—the number that makes the cover page—printed a new high at $192.4 trillion, three-month annualized growth holding at 7.8%. One layer down, the Shadow Monetary Base (SMB), the granular slice that actually leads risk assets by about thirteen weeks, flipped from +1.8% to −6.3% three-month annualized in a single print. The two have moved in tandem for most of this cycle. This week they came apart. The headline is the cover page. The SMB is the signal.
We had positioned to add to our Bitcoin short at $85,000—the band the prior week’s rejection thesis named. The market never reached it. Spot peaked around $82,000 and rolled over, and the rejection effectively happened at the $82,000 dealer-gamma cluster, below the named band. The existing net-short book paid through the move that did happen—wallet equity up 12.83% on the week.
Underneath the price, the on-chain structure confirmed the turn. Bitcoin reclaimed the True Market Mean (TMM) at $78,300 during the rally and lost it the same week; bull-market transitions are built over weeks to months of consolidation around that level, not a single decisive candle through it. The Realized Profit and Loss Ratio (RPLR) sits at 1.8, below the 2.0 that confirms genuine buy-side recovery. And the dominant negative-gamma cluster relocated from above spot, where it had dampened rallies into $82,000, to $75,000—just below spot—where dealer hedging now amplifies a move down through the strike.
The headline says liquidity is expanding. The engine, the on-chain structure, and the macro all say the opposite. We read the next several weeks as contraction toward the Glassnode-named cohort floors—first $76,900, then $71,400—not a clean turn at current levels. Our perp book stays net short.
Geopolitical Tape
Saudi independent kinetic action against Iran in March
United Arab Emirates strikes
Japanese investors net-selling $29.6 billion of U.S. bonds in the first quarter of 2026, the most since the second quarter of 2022
U.K. gilts at multi-decade highs amid a Labour leadership challenge
the U.S. 30-year Treasury at post-2007 highs
Saudi April crude production at its lowest since 1990
Pakistan deploying 8,000 troops, a jet squadron, and air-defense assets to Saudi Arabia
NATO’s Secretary General naming a Hormuz mission at the alliance-leadership tier
a report of Chinese training of 200 Russian troops in drone warfare, combat-deployed to Crimea and Zaporizhzhia
South Korea beginning nuclear-submarine procurement without U.S. sign-off
🔴 This week’s global-flow read is firing.
The Commodity Tape
Oil—West Texas Intermediate (WTI) sustained above its 100-week moving average, with that average rising over a quarterly window.
WTI sits at $105 against a 100-week line of $71.44—47.9% above it—and the line itself has risen 11.7% over the past quarter. Both firing conditions are met. The tell is that the Middle East risk expressed itself in oil this week rather than somewhere else: when a widening Iran conflict prices into crude directly, the energy channel is doing the work, and the energy channel is the one that feeds straight back into the inflation print keeping every central bank hawkish. Oil firing here is not a standalone commodity story; it is the transmission line between the geopolitics above and the macro below.
🔴 This week’s oil read is firing.
The Equity Tape
Equities—the S&P 500 (SPY) closing below its 20-day moving average ten sessions in a row.
SPY sits at $734, 1.9% above its 20-day average. The pillar is not active, and that inactivity is the only thing standing between two firing geopolitical pillars and full convergence of confirmed stress. It is the condition that lets us breathe another day. It is also the most fragile: today brings the FOMC minutes from Powell’s final April 29 meeting—a four-dissent record not seen since October 1992—alongside Nvidia earnings, and that combination is the proximate path to a pillar firing if it produces an equity correction. We are one print away from the read changing.
🟢 This week’s equity pillar is set on CHILL.
— Geopolitical Intelligence Officer (Margaux Lindqvist) · Chief Macro Strategist (Theodore Brennan)
Hard Assets
Gold’s quiet this week is doing more work than its level. It sits at $4,501, and the two hard-money trades are pulling apart rather than confirming each other. The mechanical reads on the two ratios:
BTC/Gold ratio at $77,428 / $4,501 = 17.20×. Below the 20× early-bull confirmation line, and a universe away from the 40× exit reference the prior cycle peak printed.
🔴 This week’s BTC/Gold ratio sits below the early-bull line.
Gold/Oil ratio at $4,501 / $105 = 42.9×. Down from 52.4× on May 5 and 45.5× on May 12, continuing to compress toward Howell’s long-run mean of about 20×. The compression matters less than its mechanism: it is happening through oil rising, not gold rising.
The ratio mean-reverts toward 20×. The path now runs through oil up and gold sideways-to-down, not through gold up—and that is a materially more defensive picture for anyone holding gold as the debasement trade.
🔴 This week’s Gold/Oil ratio is compressing through oil, not gold.
— Hard Asset Strategist (Marcus Vasquez)
Position Tape
Size and direction. We carry $8,796,488 in wallet equity today, up $999,054—12.83%—over six sessions in which Bitcoin fell 3.06% and Solana (SOL) fell 6.84%. The net-short construction paid through both moves. The perp book is net short on both legs.
Funding Rate Carry. Running positive at $381,865 annualized, 4.34% of equity in the income direction—the net-short Bitcoin leg receives funding. The wait is being paid for.
Position vs. thesis. The book is positioned for the bear-continuation read. If that read fails—on any one of the five conditions named in the Forward Thesis below—the position re-evaluates at the next weekly run.
— Lead Trader (Jordi Federer)
Liquidity Tape
Michael Howell’s granular liquidity measures plot the SMB against aggregate Global Liquidity. The two have tracked each other through most of the cycle. They diverged this week. The headline rose to $192.4 trillion, three-month annualized growth steady at 7.8%; the SMB dropped to $110.1 trillion, three-month annualized swinging to −6.3% from last week’s +1.8%. Headline liquidity made a new high while Bitcoin fell. That gap is the story.
The gap is the work of two things only: stable Fed liquidity injections and a suppressed MOVE index, the measure of Treasury-bond implied volatility. Lower MOVE means lower haircuts on collateral, which lifts the collateral multiplier, which lifts the aggregate even when central-bank balance-sheet activity is flat or negative. MOVE averaged near 70 last week, around four-year lows—a level flatly inconsistent with the current geopolitical landscape. It has since established itself in the 80s, breaking the 80 threshold this week. If it holds or extends there, the multiplier expansion reverses and the headline number falls toward the SMB—the divergence closes by the headline coming down, not by the engine coming up. The expansion was already being capped from the other side by a stronger dollar and weaker PBoC and European liquidity.
This matters because of timing. The SMB leads risk assets by about thirteen weeks, which puts this week’s −6.3% trough into a price-headwind window in June and July. The move you can see in the price was not driven by the engine. When the engine’s signal transmits on schedule, it lands as a second source of pressure on a market that has already rolled over. Howell’s out-of-cadence piece this week put the structure plainly: a six-to-twelve-month drawdown in the 2021–2022 style—falling liquidity, rising volatility, equity losses—absent a Warsh-led Fed intervening against the inflation threat.
We are one week further from a bull market than we were a week ago.
🔴 This week’s liquidity read points to risk-off.
— Global Liquidity Director (Julian Harlow)
On-Chain Tape
The on-chain picture turned defensive across cohort, flow, and positioning at once. Bitcoin tagged the True Market Mean at $78,300 during the rally and lost it; a deeper correction from here reframes the whole move as a local top within the ongoing bear. The recent-accumulation cohort that bought near $78,200 is already underwater, and below spot the February–April accumulation cohort sits at $71,400—the level Glassnode names this week as the most probable near-term support, a cohort with a dwindling profit margin and a growing incentive to protect it before conditions deteriorate further.
The flow data says demand never showed up to meet the rally. The Realized Profit and Loss Ratio (RPLR)—realized profits against realized losses—spiked from a February low of 0.4 to 1.8 as holders sold into strength, but profit-taking is selling, and the price tells us demand did not recover enough to absorb the volume of sellers using the rally as an exit. The 30-day reading sits below the 2.0 that would confirm a genuine buy-side recovery. Spot Cumulative Volume Delta (CVD) bias stayed negative into the pullback; Binance recovered modestly from deeply negative levels while Coinbase stayed subdued. Glassnode’s framing is stronger offshore speculative participation against weaker U.S. institutional spot demand—the multi-channel positive of one week ago losing its Coinbase leg.
Positioning compounds it. Open interest in Chicago Mercantile Exchange (CME) futures kept recovering while ETF accumulation cooled—a market increasingly driven by futures positioning rather than spot buying, with funding staying positive and firming despite spot weakness, the signature of leveraged longs paying to hold exposure through a tape that contradicts them. The options layer matched the tone: one-month implied volatility rebuilt from 32% to 36% across the week, the volatility risk premium widened to about ten points, and the 25-delta skew turned bearish across the curve, most sharply at the front end where it ran from 2.7% to 6.2%. Put-buying took more than 90% of taker premium over the last 24 hours.
The cleanest structural read is in the gamma. Last week the dominant negative-gamma cluster sat at $82,000, above spot, where dealer hedging dampened rallies into the strike. This week it relocated to $75,000—just below spot—with about 2.5billion of exposure.
🔴 This week’s on-chain read is defensive.
— Capital Flow Analyst (Priya Sandoval) · Fundamental Research Analyst (Charlotte Donovan)
Macro Tape
The macro tape across May 14 to 20 loaded the same direction every session, and it is the direction that removes the bull case’s one requirement—a Fed easing path. April producer prices ran 6.0% year over year, the highest since December 2022; the 30-year Treasury auctioned above 5% for the first time since 2007; and Bank of America formally abandoned its 2026 rate-cut call, pushing the first cut to the second half of 2027. Kevin Warsh was confirmed as Fed Chair 51-45, the FOMC’s most consistent dovish dissenter resigned effective his inauguration, and interest-rate futures crossed better-than-even odds of a hike by January 2027—then ran to roughly 80% priced for a hike this year by week’s end.
This is no longer only a Fed story. An ECB Governing Council member named a June hike “quite likely” if the Iran war does not end—the first to put June on the table with explicit war-conditionality—and Iceland delivered its second hike since the Middle East outbreak. Global long-ends confirmed the regime: the U.K. at multi-decade-high yields, Japan’s 30-year at 4.2% and post-1999 highs, the South Korean equity market tripping its circuit breaker. Three central banks are being pushed by an energy shock rather than pulled by growth, at the same time. The macro that delivered this week’s weakness is the same macro that validates the read behind it.
🔴 This week’s macro read points to a risk-off regime.
— Chief Macro Strategist (Theodore Brennan)
Forward Thesis
We expect Bitcoin’s next material move to be contraction to the Glassnode-named cohort floors, not a retest of the $80,000 short-add zone from below. The prior week anchored a rejection on the 85, 000–87,000 band; the market never tagged it, peaking near $82,000 and rolling over at the dealer-gamma cluster below. The reframe for the next several weeks is that the $80,000 zone is the rejection band that already failed beneath it, not the next operational contact. The next contacts are the floors: $76,900 first—the near-term cohort floor, currently holding by a few hundred dollars on the close—then $71,400, the February–April accumulation cost basis. Between $76,900 and $75,000 sits the relocated gamma cluster, the zone where dealer hedging amplifies a move down. The path through that band is structurally faster than the symmetric path back up to $80,000.
The book stays net short into both branches. If $76,900 breaks and the market traverses the $75,000 gamma band, the $66,000 Bitcoin long add becomes the next evaluation. If instead the market reclaims $76,900 and approaches $80,000 from below with sustained spot demand—including Coinbase joining the bid—we re-evaluate the standing rejection thesis. The current on-chain read places that bounce-and-reclaim scenario as the lower-probability path.
What would change our mind. Five conditions, any one of which triggers a Position Tape re-evaluation at the next weekly run:
The SMB three-month annualized clearly positive on the next print. It is −6.3% now; this week’s 8.1-point reversal makes this the most demanding single invalidation, and a bounce above zero is mechanically possible only under Fed-Treasury intervention that Howell himself names as unsustainable.
The RPLR 30-day reading sustained above 2.0 across multiple weeks. It is 1.8 now; a single cross is necessary but not sufficient, and sustained is what would confirm.
A Bitcoin weekly close above $80,000 with sustained spot demand, including Coinbase CVD joining Binance—not a wick, not a derivatives squeeze. Coinbase is subdued; the multi-channel positive of one week ago has lost a channel.
**ETF inflows back to 1.5billion − plusweeklynet, sustainedtwoconsecutiveweeks. * * Weareintheoppositeregime : thecurrentweekisrunning−1.45 billion.
The GEO stress equity pillar firing. SPY closing below its 20-day MA ten sessions running; the counter is 0/10, and today’s FOMC minutes plus Nvidia earnings are the proximate path to it. This is the one condition that would escalate the read rather than relax it.
Two simultaneous partial firings across these conditions trigger an interim re-evaluation outside the weekly cadence.
— Lead Trader (Jordi Federer)
Watchlist
BTC at $76,900—the near-term cohort floor. Break-and-hold below opens contraction toward $71,400; this replaces the old 85, 000–87,000 rejection band as the operative live level.
BTC at $75,000—the relocated dealer-gamma cluster. The zone between $76,900 and $75,000 is where dealer hedging amplifies a move down.
BTC at $71,400—the February–April accumulation cost basis. If $76,900 breaks, this is the second-test level for the long-add evaluation.
BTC at $80,000—a test-from-below event only if price reverses up through it with sustained spot demand.
RPLR 30-day reading toward 2.0—currently 1.8. Direction matters more than any single print; a sustained move to 2.0 with a weekly close above is the bear-invalidation signal.
SMB three-month annualized, next print—currently −6.3%. A bounce above zero resets the read materially; the June–July transmission window is the structural watch.
MOVE index—currently in the 80s, having broken 80. A fall back below 70 means the Treasury suppression machinery is still working; holding above means the headline-liquidity multiplier reverses.
U.S. 30-year Treasury yield—around 5.18%, the post-2007 high tier, Howell’s bearish-flattening watch.
ETF flow magnitude and breadth—the current week is −$1.45 billion across three negative prints; sustained net inflows above $1.5 billion are the invalidation threshold.
Coinbase vs Binance CVD breadth—Coinbase subdued, Binance recovered modestly. The bid rejoining on Coinbase is the contra-thesis confirmation.
PBoC liquidity injection trend—paused per Howell’s May 19 chart. The pause sustaining hits gold through the Shanghai-priced yuan-gold leg.
The Hayloo Unchained Team
Chief Macro Strategist—Theodore Brennan. Macroeconomic cycles, central bank policy, growth and recession dynamics, sovereign debt, currency regimes. Anchors daily and weekly reads to the current macro regime. Flags regime shifts as they materialize.
Geopolitical Intelligence Officer—Margaux Lindqvist. Geopolitical risk, capital flow implications of conflict and alliance shifts, sanctions, resource competition, regime stability. Integrates the daily news brief into the daily synthesis. Maps geopolitical events to severe-stress convergence components and to capital flow implications.
Hard Asset Strategist—Marcus Vasquez. All assets priced in gold terms. Responsible for identifying dollar-devaluation mispricing. Converts conventional valuations to gold-denominated equivalents as standard practice. Surfaces gold-denominated reads when the BTC/Gold ratio approaches structural levels or when the dollar regime shows signs of inflection.
Inflation & Real Asset Analyst—Sienna Whitfield. Assets priced against inflation. Consumer and producer prices, breakevens, real yields, commodity structures. Flags when nominal gains are real losses. Cross-checks apparent profit-taking—ensures harvest decisions are evaluated against real returns, not nominal.
Global Liquidity Director—Julian Harlow. Michael Howell’s Global Liquidity framework. Liquidity cycles, central bank balance sheets, cross-border credit creation. Primary interpreter of the weekly Howell report. Timeframe: years and cycles, not weeks. Anchors the team’s months-to-years time horizon.
Capital Flow Analyst—Priya Sandoval. Where liquidity moves once created. Cross-asset flows, fund positioning, ETF mechanics, derivatives positioning, futures term structure. Joint owner with the Fundamental Research Analyst of the weekly Glassnode read. Tracks where new liquidity routes—ETF flows, perpetual positioning, derivatives skew.
Technical Analyst—Lukas Marchetti. Price action, structure, and pattern—calibrated to match the liquidity cycle timeframe. Weekly and monthly charts are primary; daily charts tactical; sub-daily charts activated only when the team has made a directional call and is executing an entry or take-profit. Technicals are treated as lagging confirmation of forward-looking macro and liquidity signals. Divergence between technicals and the macro thesis is expected and discussed, not resolved by hierarchy.
Fundamental Research Analyst—Charlotte Donovan. Asset-level fundamentals. For Bitcoin: network economics, supply dynamics, miner behavior, adoption curves. For other assets as composition expands, an analogous fundamental frame. Joint owner with the Capital Flow Analyst of the weekly Glassnode read. Tracks supply-side dynamics—long- and short-term-holder cohorts, miner state, on-chain cost-basis structure.
Lead Trader—Hayloo Unchained. Final decision authority on all position decisions. Domain: the book itself—capital allocation across the Bitcoin leg, the SOL leg, and the Bitcoin spot collateral reserve; entry, harvest, and restructure calls; risk tolerance and conviction-sizing at execution; the standing thesis that the eight specialists pressure-test against. Adjudicates specialist disagreement and rules on structural questions. Receives the team’s reads, challenges, and recommendations—then decides. The machine does not move without him.
The information is provided for information purposes only and on the basis that it will not be relied upon. No information contained herein constitutes a personal recommendation or investment advice.
The information (including any expressions of opinion or forecast) has been obtained from, or is based on, sources believed by the author to be reliable, but are not guaranteed as to their accuracy or completeness and should not be relied upon. The information is provided without obligation on the part of the author and on the understanding that any person who acts upon it or changes his investment position in reliance on it does so entirely at his own risk. The information does not constitute an offer to buy or sell or an invitation to make an offer to buy or sell any financial instrument.
Information is current only as at the date it is first posted and may no longer be true or complete when viewed by you. All information may be changed or amended without prior notice.
No representation, warranty or undertaking is given as to the accuracy or completeness of the information by the author and no liability is accepted by the author for the accuracy or completeness of such information. In no event will the author be liable to any person for any direct, indirect, special, or consequential damages arising out of any use of the information, including, without limitation, any lost profits.
You should be aware that the Internet is not a completely reliable transmission medium. The author does not accept any liability for any data transmission errors such as data loss or damage or alteration of any kind, including, but not limited to any direct, indirect or consequential damage, arising out of the use of the product or services referred to herein.
The materials provided here including text, photographs and other images, are protected by copyright and/or other intellectual property rights. All copyright (and any other intellectual property rights) in these materials is either owned by the author, or is used by the author under licence.