


Tape of the Week
Bitcoin printed the first sub-$60,000 tape since 2024, and every long-duration gauge we watch sits where cycle bottoms historically form. The bottoming tells are stacking up around Bitcoin’s stall at $61,000. But with spot demand, exchange-traded fund (ETF) inflows, and a Coinbase bid all missing from the picture, finding a price is not finding a bottom.
Global Liquidity keeps rolling over. The chip rout has SPY four closes below its 20-day average, and the hard-asset debasement trades are losing steam. One split runs the other way: the altcoins that lost asymmetrically against Bitcoin are catching a bid while Bitcoin keeps bleeding. We signal the regime change, not the direction.
Our perp book remains net short for the gap between Bitcoin’s capitulation price and a confirmed bottom. The next four to twelve weeks read lower-to-choppy, with real second-leg risk into late summer — the spring’s liquidity fade hitting the tape as sticky inflation meets an overleveraged AI boom. That is where we expect buying opportunities to open between $45K and $54K. For now, we pulled the ladder back — 45, 000–54,000 is where we next debate adding to the long leg. A cycle bottom and a further 20% drop have coexisted before.
Hayloo’s Macro Board
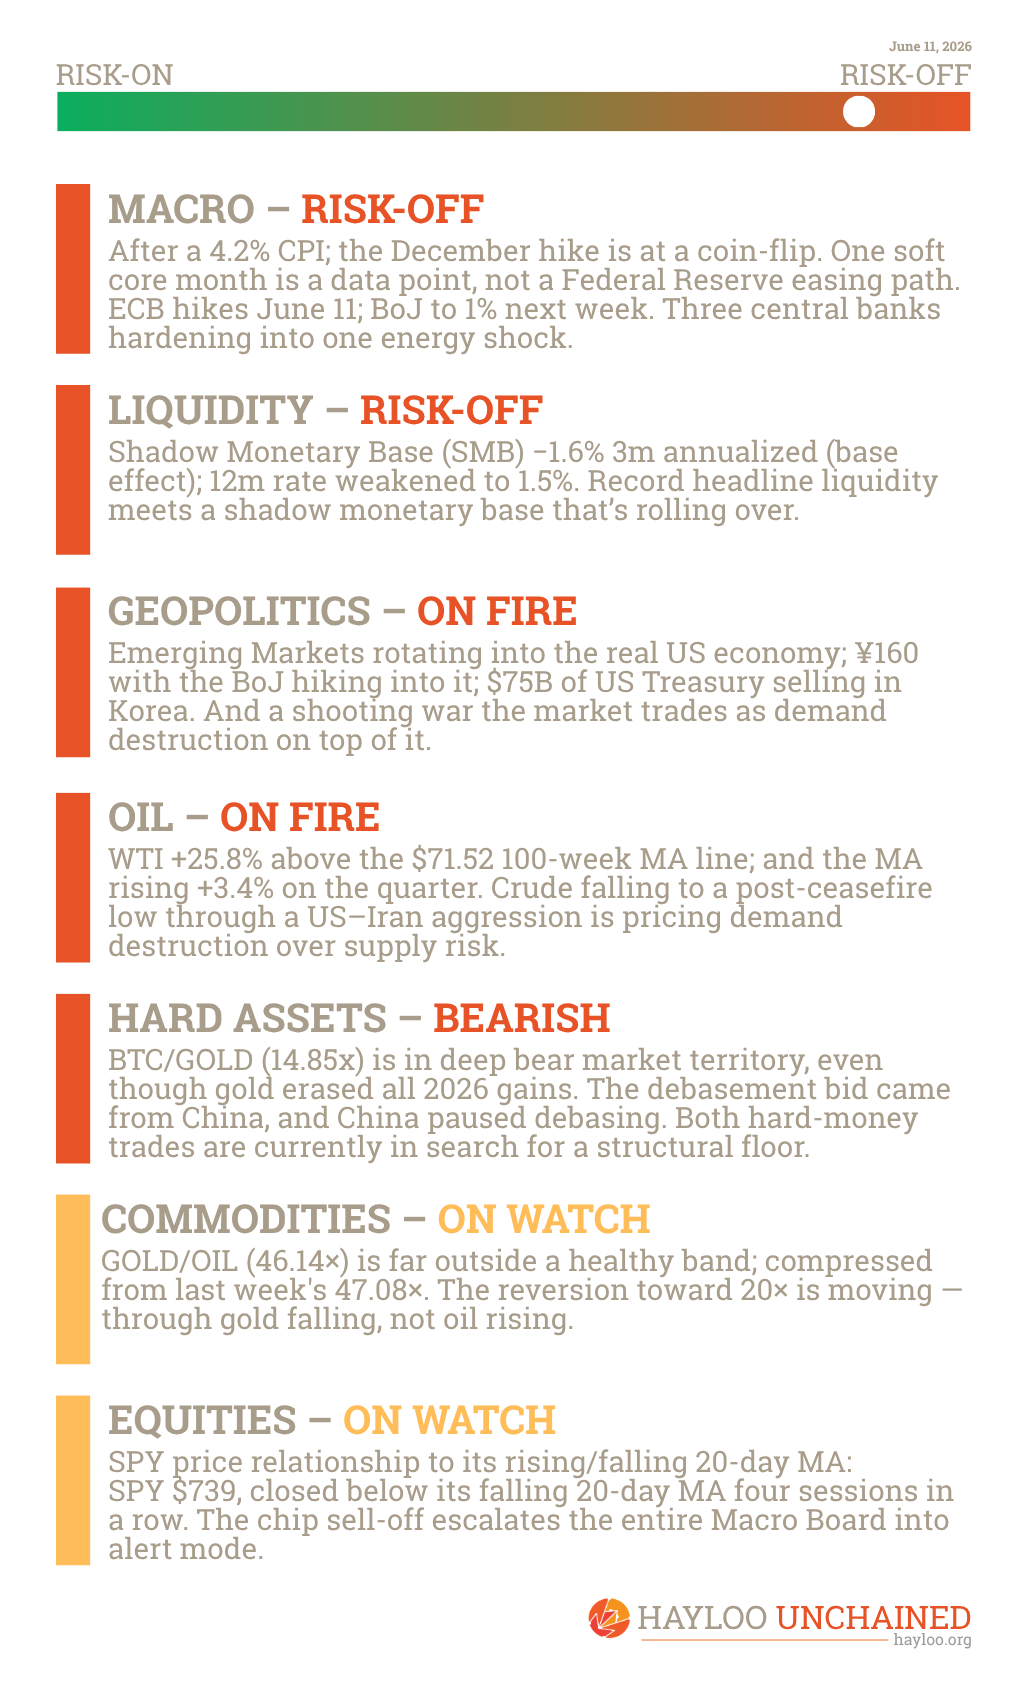
Macro Tape
May Consumer Price Index (CPI) printed 4.2% — a three-year high — and the market took it dovishly, pulling December to a coin-flip because the core held in line. Do not over-read it. The three-month run is 8.2% annualized, there is no sign the energy spike has stopped bleeding through, and TSMC declined to rule out price increases this week — the inflation passthrough is arriving, not closing.
Even the payrolls beat that opened the week was a jobs beat, not a wage beat, which leaves the inflation push exactly where the energy and the chips are. And the nudge lands on one leg of a three-central-bank hardening: the European Central Bank (ECB) hikes June 11 into contracting output, the Bank of Japan (BoJ) goes to 1% next week, and Kevin Warsh chairs his first Federal Open Market Committee (FOMC) meeting June 16–17 with a president on tape telling him not to move.
🔴 This week’s macro tape holds the risk-off regime, with one dovish counter-note.
— Chief Macro Strategist (Theodore Brennan)
Geopolitical Tape
The Iran war’s new aggressions read de-escalatory — escalation in the headlines, restraint in the targets — and crude’s response was to fall to a post-ceasefire low. A market that sells oil into a widening shooting war is pricing demand destruction over supply risk. What it still cannot price is the supply side itself: nobody knows how much is actually getting out of Hormuz.
🔴 This week’s geopolitical landscape is on fire.
— Geopolitical Intelligence Officer (Margaux Lindqvist)
The Commodity Tape
The drop in oil is a read; the price holding above a rising long-term average is the story. WTI sits +25.8% above its 100-week MA at $71.52, and no daily print moves that — the read is the regime, and the regime is an elevated oil price with the supply route closed. What changed this week is the market’s refusal to price that route: supply risk nobody will pay for is convexity if the off-switch fails.
🔴 This week’s Oil Price stays on fire.
— Hard Asset Strategist (Marcus Vasquez) · Geopolitical Intelligence Officer (Margaux Lindqvist)
The Equity Tape
The Broadcom crack we named last week became the rout. The Philadelphia semiconductor index fell 10% for its worst week in six years, Nvidia slipped below $5 trillion, Korea took a circuit breaker on Monday’s open, and the relief bounce that followed — SK Hynix up 15% — died inside a day: Micron −4.2% on the relapse, with sell-side correction calls of 6–7% now landing. The open question is the one that matters for the regime: whether higher rates turn a momentum unwind — the chip index is still up 70% on the year — into a valuation rethink, the way 2022 did. The breadth already votes that way; on the bounce day itself, 60% of the S&P 500 closed red.
🟠 This week’s equity pillar is on our watchlist.
— Capital Flow Analyst (Priya Sandoval) · Chief Macro Strategist (Theodore Brennan)
Hard Assets
Gold gave back its year. It traded below $4,200 for the first time since March 23 — and it did it while oil held elevated and the Middle East stayed kinetic. A safe-haven asset that cannot catch a bid into a shooting war is telling you where its bid actually came from: the People’s Bank of China (PBoC) tap, and the tap is off. Silver runs the same trade — through $70 early in the week, near $64 now, a $1.50 intraday pop on the CPI print notwithstanding.
Hard-money trades are deflating; the line we watch is unchanged: BTC/Gold at 14.85× sits far below the 20× early-bull confirmation. Gold/Oil at 46.14×, compressed from 47.08× — the mean reversion toward the long-run ~20× we track is finally moving, and it is moving through the leg we said it would: gold falling, not oil rising.
🔴 This week’s hard-asset ratios stay in bear-market territory.
— Hard Asset Strategist (Marcus Vasquez)
Liquidity Tape
Global Liquidity printed a record $193.5 trillion this week, and the height is engineered: Treasury-bond volatility sits exactly at its year-to-date average through a shooting war, record issuance, and a three-year-high inflation print — a calm attributed to active Treasury volatility management.
One layer down, the engine is broken. The Shadow Monetary Base improved only on base effects — the twelve-month trend actually weakened — with the PBoC tightening faster, the Fed’s support fading, and risk appetite peaking in late-cycle speculation.
The plumbing agrees — the reverse-repo cushion is functionally empty, stablecoins are shrinking, private credit is gating — and the buffer that funded the last leg of risk is gone.
🔴 This week’s liquidity tape points to risk-off, with more headwinds ahead.
— Global Liquidity Director (Julian Harlow)
Hayloo’s Crypto Board
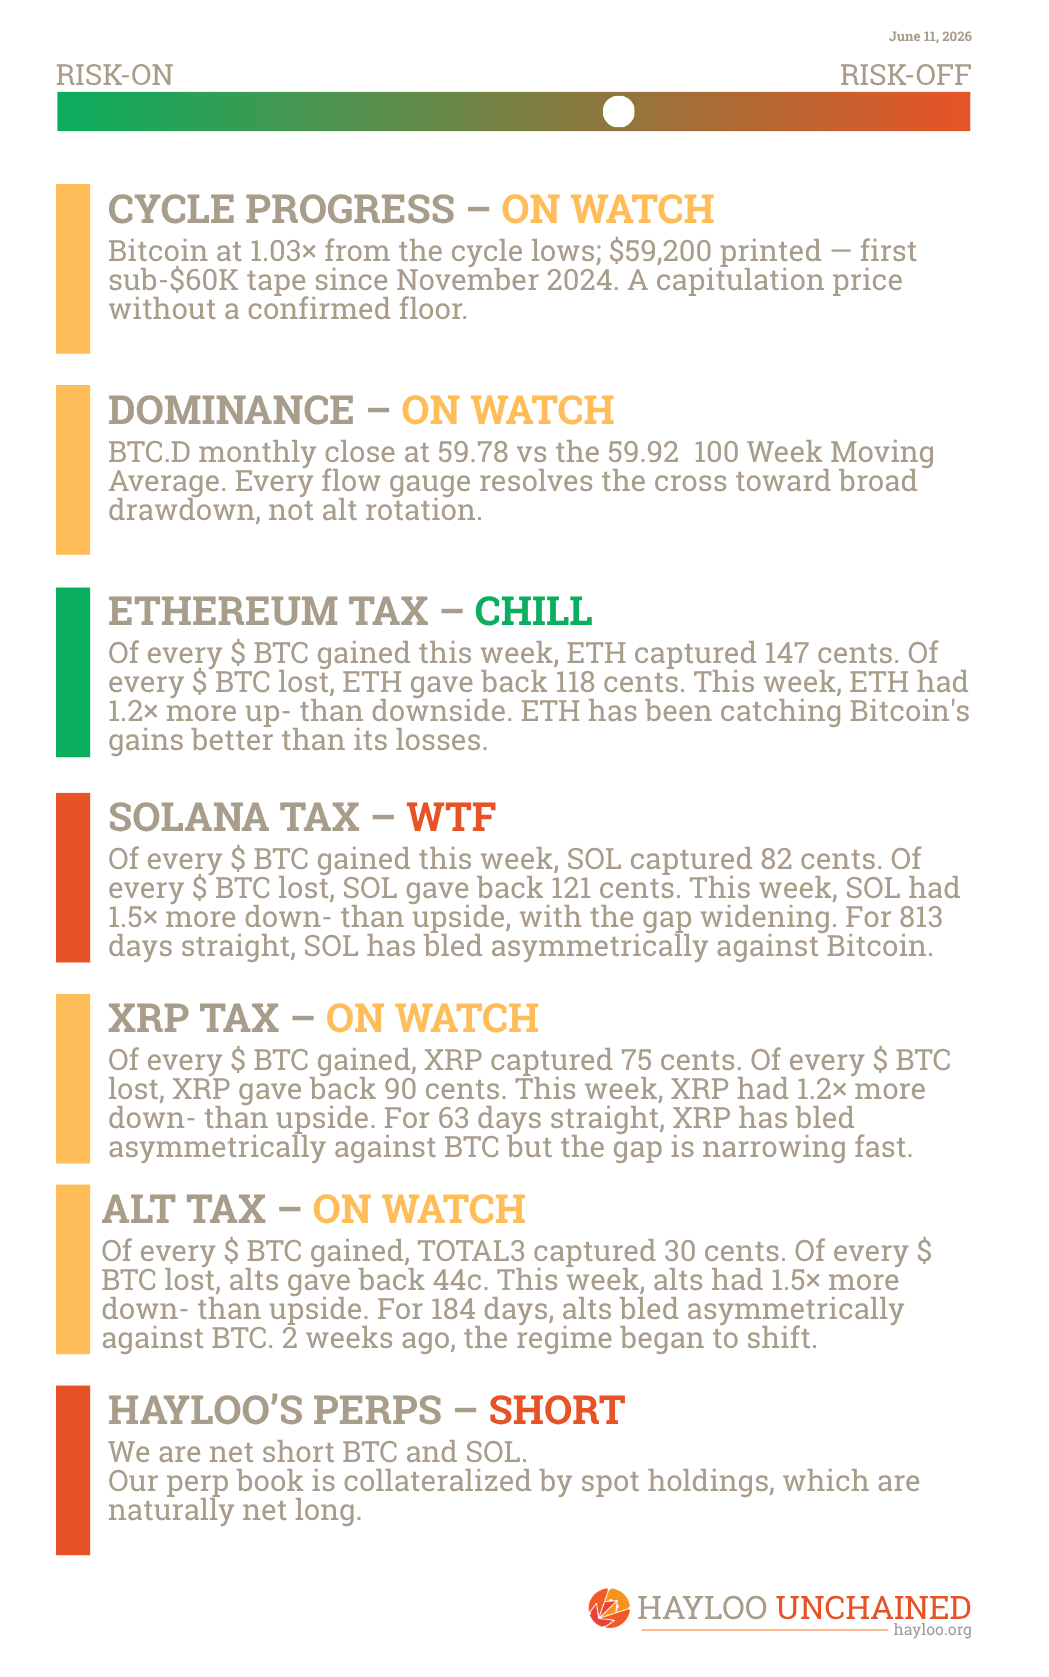
On-Chain Tape
Glassnode’s valuation work sits at the extremes that historically contain bottoms: its long-horizon AVIV gauge prints −1.06 against a cycle low of −1.09, and more than 95% of recent buyers are underwater. That is capitulation depth. Glassnode still reads it as exhaustion pausing rather than a floor forming, and the reason is demand — there isn’t any.
Coinbase trades at a discount, realized flows print fear rather than bull-market capital, and the treasury-company bid that ran half a billion dollars a day through May has been near zero since. The ETFs are four weeks into outflow, about $5.6 billion all told — though the bleed is slowing, and the average ETF holder now sits at breakeven, exactly where forced selling historically resolves rather than idles.
The constructive notes are real, and they are fuel, not demand. The leverage below is cleared, dealer hedging flips supportive overhead, options are defensive to late-capitulation extremes, and long-term holders are sitting on their coins — a market primed to move fast in whichever direction demand picks.
🔴 This week’s on-chain metrics deepen into capitulation.
— Capital Flow Analyst (Priya Sandoval) · Fundamental Research Analyst (Charlotte Donovan)
The Alt Tax
After 184 quiet days, the Trailing-altcoins regime is no longer sitting still. The altcoin beta’s asymmetry gap bottomed on May 31 and has snapped back, tripping the contraction flag for the second straight week — the signal our backtest fires before regime turns, in either direction. The path is snap-and-chop rather than a clean close toward zero, and a relationship moving this fast puts any read beyond three weeks on shaky ground.
Bitcoin dominance carries the other half of the truth: 58.9% and falling, 2.3 points off the May 5 top and below both its 50- and 150-day averages — alts gaining market share while still lagging Bitcoin on beta. The two point opposite ways; we do not forecast which side resolves — dominance is a thermometer, confirming Bitcoin’s bleed, not forecasting an altcoin renaissance.
🟠 This week’s Alt Tax is on our watchlist.
Hayloo’s Perp Book
Size and direction. Our perp book is net short: roughly 202 BTC short net on the Bitcoin perp (12.4million at mark)and 36, 720 SOL short net (2.4 million at mark).
The harvest, plainly. We realized $1,671,068 in profits at the $61,000 zone we named last week — the break went through it, the bounce returned to it, the June 10 close sat on it. The decision taken was to wait. We do not trade into a demand vacuum because the price is statistically cheap.
Funding Rate Carry — the first breach. At yesterday’s rates our funding cost runs −$445,904 annualized, −4.66% of equity — for the first time this year, our patience stopped being paid. The waiting carries a price. When shorts get crowded, that is a capitulation tell.
Next levels that fire. Downside: BTC $54,000 and SOL $55, both Long Add / Short Take-Profit. Overhead, the structure that has to be reclaimed: the $71,400 and $76,900 cohort cost bases now sit as resistance, and the reclaim that matters is a weekly close above both with spot demand attached.
Position vs. thesis. The book is positioned for the bear-continuation read. Our read moved toward escalation, not relief, and the five conditions in the Forward Thesis below govern it.
— Lead Trader (Jordi Federer)
🔴 Hayloo’s perp book is net short.
Forward Thesis
The next four to twelve weeks read lower-to-choppy, with the real risk concentrated in a second leg rather than a clean V at current levels. Every demand channel that confirms a durable low is off, realized losses are still rising into the low rather than drying up.
The liquidity cycle is rolling over, and another 20% down — roughly $50K Bitcoin — is within imagination. A cycle bottom and a further 20% drop have coexisted before.
The macro hardens across three central banks into an energy shock, the plumbing cushion is gone, and the 13-week transmission from the late-May SMB trough still lands its deepest price-headwind window in late August — pressure scheduled to arrive on a market that has already broken once. The named supports below the cleared structure are $53,900 — the Realized Price, the bear-value floor — and the $61,000 200-week MA the tape is sitting on. Our perp book stays net short.
What would change our mind. Five conditions:
SMB three-month annualized clearly positive on the next print. It sits at −1.6% — two consecutive less-negative readings, but the improvement is base effect and the 12-month rate weakened to 1.5%. Not the reset.
RPLR — the on-chain realized profit/loss ratio — sustained above 2.0 across multiple weeks. The print sits at −1.7, outside the −1.0 fear band, with the severe-capitulation marker approaching from the other side. Further from satisfaction than last week.
A BTC weekly close above $76K with sustained spot demand, including Coinbase order flow joining the bid.
ETF inflows back to $1.5 billion-plus weekly net, sustained for two consecutive weeks.
Ten consecutive SPY closes below the 20-day MA. The counter is at 3 of 10 and counting, with the chip relapse the live path. This is the one condition that escalates our view rather than relaxing the read.
— Lead Trader (Jordi Federer)
Watchlist
SPY versus its 20-day MA
BTC at $54,000 — with the $53,900 Realized Price just below it.
The funding rate daily prints. Whether funding confirms the flip or reverts to the positive 7-day average decides whether this week’s breach was noise or capitulation.
ETF flow, second derivative. The ETF MVRV (the average holder’s market value against cost) sits at 1.01 — breakeven is where forced selling resolves, not idles.
SOL, Ethereum, and XRP — persistence of the alt bid. Ethereum’s price action and the SOL and XRP ETF inflows against the BTC bleed are the signal that needs to resolve.
Gold at the $4,000 zone. Gold/Oil and BTC/Gold ratios against their mean-reversion paths.
Crude and Hormuz. Supply risk the market refuses to price is convexity if the off-switch fails.
BTC.D — dominance below the 100-week MA is a regime that needs directional input.
Four Central Banks Outbid One War

Tehran declared the Strait of Hormuz closed to all vessels. Trump promised tonight’s bombing would run larger than last night’s. Keep it simple, stupid. Washington disputes the closure and says comme…
The Hayloo Unchained Team
Chief Macro Strategist — Theodore Brennan. Macroeconomic cycles, central bank policy, growth and recession dynamics, sovereign debt, currency regimes. Flags regime shifts as they materialize.
Geopolitical Intelligence Officer — Margaux Lindqvist. Geopolitical risk, capital flow implications of conflict and alliance shifts, sanctions, resource competition, regime stability. Maps geopolitical events to capital flow implications.
Hard Asset Strategist — Marcus Vasquez. Responsible for identifying dollar-devaluation mispricing. Surfaces gold-denominated reads when the dollar regime shows signs of inflection.
Inflation & Real Asset Analyst — Sienna Whitfield. Assets priced against inflation. CPI, PPI, breakevens, real yields, commodity structures. Flags when nominal gains are real losses. Ensures harvest decisions are evaluated against real returns, not nominal.
Global Liquidity Director — Julian Harlow. Liquidity cycles, central bank balance sheets, cross-border credit creation. Anchors the team’s months-to-years time horizon.
Capital Flow Analyst — Priya Sandoval. Cross-asset flows, fund positioning, ETF mechanics, derivatives positioning, futures term structure. Tracks where new liquidity routes, surfaces flow shifts that contradict the standing synthesis.
Technical Analyst — Lukas Marchetti. Price action, structure, and pattern — calibrated to match the liquidity cycle timeframe. Technicals are treated as lagging confirmation of forward-looking signals. Divergence between technicals and macro thesis is expected and discussed, not resolved by hierarchy.
Fundamental Research Analyst — Charlotte Donovan. Asset-level fundamentals, network economics, supply dynamics, miner behavior, adoption curves. Tracks supply-side dynamics — LTH/STH cohorts, miner state, on-chain cost-basis structure.
Lead Trader — Jordi Federer. Domain: the book itself — capital allocation across perp positions and the spot collateral reserve; entry, harvest, and restructure calls; risk tolerance and conviction-sizing at execution. Hayloo is unchained by him
The information is provided for information purposes only and on the basis that it will not be relied upon. No information contained herein constitutes a personal recommendation or investment advice.
The information (including any expressions of opinion or forecast) has been obtained from, or is based on, sources believed by the author to be reliable, but are not guaranteed as to their accuracy or completeness and should not be relied upon. The information is provided without obligation on the part of the author and on the understanding that any person who acts upon it or changes his investment position in reliance on it does so entirely at his own risk. The information does not constitute an offer to buy or sell or an invitation to make an offer to buy or sell any financial instrument.
Information is current only as at the date it is first posted and may no longer be true or complete when viewed by you. All information may be changed or amended without prior notice.
No representation, warranty or undertaking is given as to the accuracy or completeness of the information by the author and no liability is accepted by the author for the accuracy or completeness of such information. In no event will the author be liable to any person for any direct, indirect, special, or consequential damages arising out of any use of the information, including, without limitation, any lost profits.
You should be aware that the Internet is not a completely reliable transmission medium. The author does not accept any liability for any data transmission errors such as data loss or damage or alteration of any kind, including, but not limited to any direct, indirect or consequential damage, arising out of the use of the product or services referred to herein.
The materials provided here including text, photographs and other images, are protected by copyright and/or other intellectual property rights. All copyright (and any other intellectual property rights) in these materials is either owned by the author, or is used by the author under licence.