


Tape of the Week
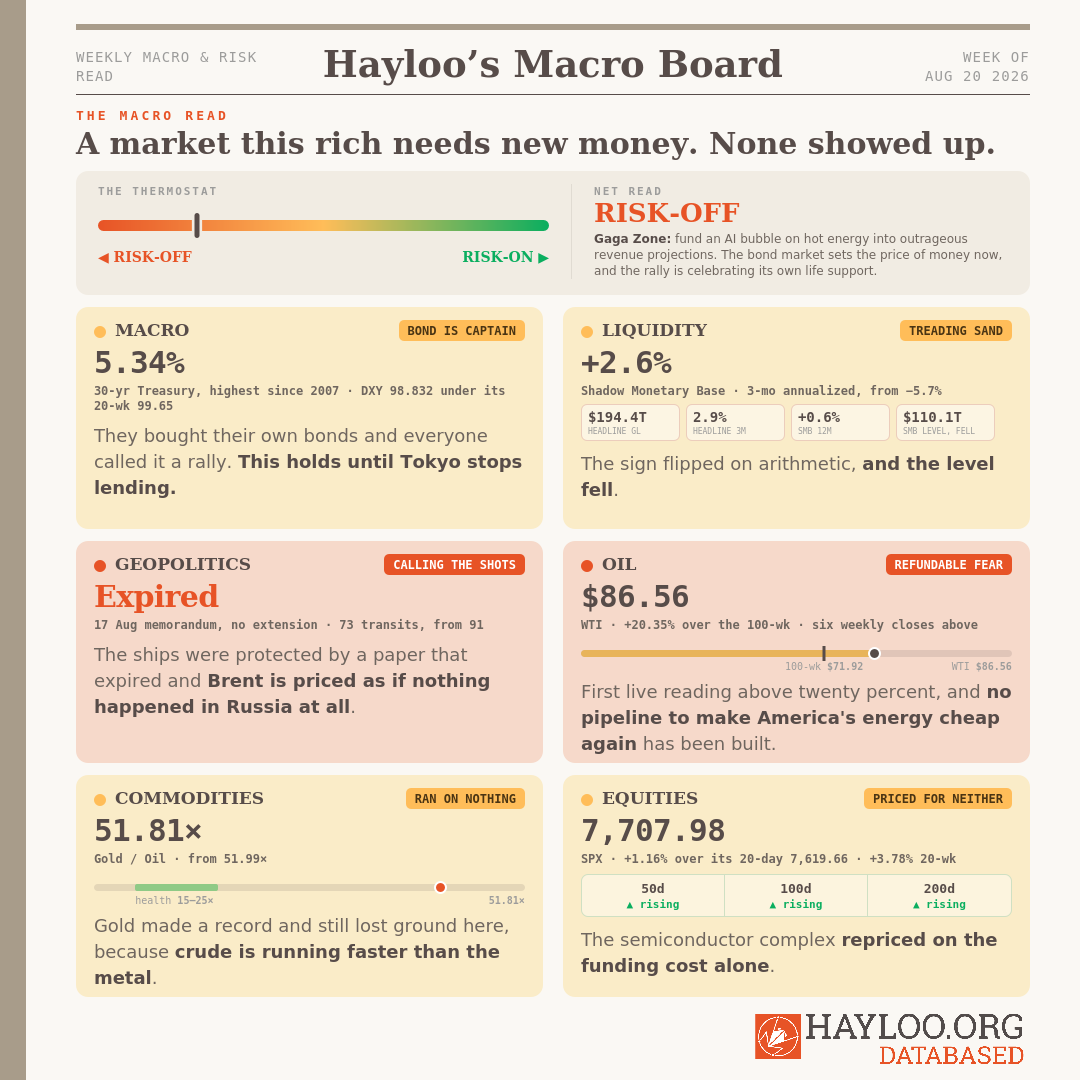
The Federal Reserve still believes it decides what money costs in America. Meanwhile the bond market had already taken over the job. When a government owes $40 trillion and adds a record $432 billion of deficit in a single month, its lenders start naming the price, and this month they named 5.34% on the thirty-year, the steepest since 2007.
So the Treasury hastily doubled buying its own debt. A droplet of two billion per month on a 432 billion hot stone, a quarter of which interest only. Yet yields fell, assets ran, Bitcoin’s drowning buyers surfaced, and the whole world turned green off an operation that added not one new dollar to the system.
That’s the story of this week — a market celebrating its own life support. It’s like a smoking cancer patient. The cigar glims as long as Japan keeps lending, and nobody asks what the AI build costs at these yields.
On our use of AI:
Measuring AI to value writing is like rating a restaurant by whether the chef used a food processor.
Humans have written machine-assisted for centuries. What never changes is who decides.
Nothing at Hayloo INC. was ever decided by a machine.
There’s no meter, no word count, no hour count, no token that tells you how much of us is in our work. We use AI, we run scripts, we process data, we ask questions, and we debate what the machine contributes.
What survives is what we defended as a team.
When it’s wrong, it’s wrong because us, the humans, signed it.
Jordi Federer, Founder, Hayloo INC.
Liquidity Tape
No new money came in this week. The pile actually shrank — $110.1 trillion from $110.3 — even though the Global Liquidity Index (GLI) Shadow Monetary Base flipped positive for the first time in six weeks, +2.6% against −5.7%.
Washington keeps the long end sedated, or tries to, borrowing short-term into an economy growing at up to 8%. It comes at no surprise that the bond market is asking for their share.
Wednesday’s buyback was met with applause by mainstream economists, celebrating a Treasury that shows up when the bond market panics.
We say the secretary fixed a pipe in the Sahara desert — there’s nowhere near enough liquidity running through his plumbing to hold up a market priced this rich.
🟠 Bessent fixed the pipe. Nobody checked if there’s water in it.
— Global Liquidity Director (Julian Harlow)
Macro Tape
Reading July’s Fed minutes, you’d think they still set the price of money — a room full of people arguing about inflation, several of them wanting a rate hike. The decision isn’t theirs anymore. The 30-year went to 5.34%, the highest since 2007, the bond market is the central bank now, and it takes fewer questions than Fed chair Kevin Warsh.
Washington owes $40 trillion, penned a record $432 billion deficit in a single month with a quarter of that just interest, and the loan sharks are naturally asking for more.
So Scott Bessent went out and bought his own debt from two doors down, twice the amount. Yields came down, the dollar cracked, Bitcoin rallied, and not one dollar moved off America’s shoulders. A headfake.
The debt just got shorter, which means the shark comes knocking down Bessent’s door more often, with the mess left for whoever’s holding the job past the midterms. That ends the day the Bank of Japan moves. People inside the building are saying the day is close.
🟠 While the Fed debates the price of money, the bond market sets it.
— Chief Macro Strategist (Theodore Brennan)
Geopolitical Tape
For sixty days, oil moved through the Strait of Hormuz — somewhat. What moved those ships was not some kind of war-power or ammunition. It was insurance. Underwriters would cover a tanker because there was a truce, and now there’s nothing.
Abu Dhabi cutting off all trade and money transfers with Iran is the thing that matters more than any headline-grabbing American threats this week.
🔴 Abu Dhabi is the captain now.
— Geopolitical Intelligence Officer (Margaux Lindqvist)
Commodity Tape
West Texas Intermediate (WTI) sits at $86.56 at the time of writing, comfortably more than 20% above its 100-week line — and the line itself is climbing. A good chunk of that cushion is the regime of fear, and fear is refundable: sign a deal and the price will show it. But only reliable infrastructure will Make America’s Energy Cheap Again. Brent sits at $91.93, priced as if Russian oil exports were flowing. They aren’t, and that’s not priced in.
🔴 No peace can build a pipeline.
— Inflation & Real Asset Analyst (Sienna Whitfield)
Hard Assets
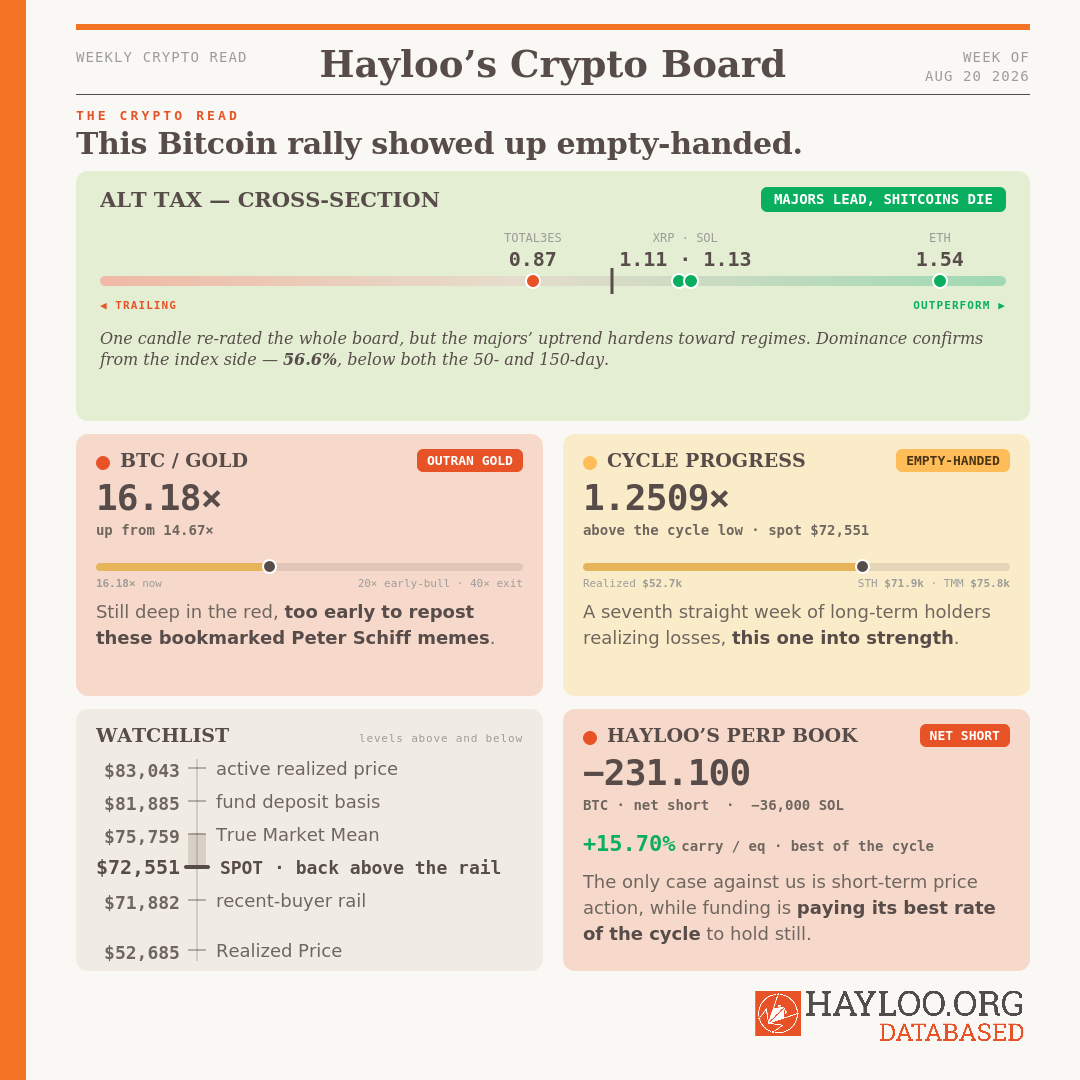
Bitcoin outran gold this week while Fed liquidity was draining. That’s the tell. Bitcoin didn’t run on liquidity — there wasn’t any — it ran on a bond-market repair headfake and the market deciding that counted as fuel for a rally. BTC/Gold went to 16.18× from 14.67×, too early to repost these bookmarked Peter Schiff memes. Gold/Oil is sitting flat because gold ran with oil this week.
🟠 Bitcoin outran gold on a headfake.
— Hard Asset Strategist (Marcus Vasquez)
Equity Tape
How do you keep an artificial-intelligence (AI) boom growing at the pace it’s priced when both money and energy are getting more expensive? Nobody’s answering that.
The S&P sits above every line and every line points up, but exposed multinationals like Samsung drop more than 7% in a day without a peep about their business. Markets aren’t trading assets anymore, they’re trading real yields, the price of money, and nothing else.
🟠 Built on borrowed money, run on expensive power, priced for neither.
— Technical Analyst (Lukas Marchetti)
This Bitcoin rally showed up empty handed
A seventh straight week of long-term holders realizing losses, this one into strength
On-Chain Tape
The average Bitcoin buyer of 2026 got made whole this week. Recent buyers went from 5.44% underwater to 2.92% in profit, and the rail at $71,882 — the level this book has named for a month as the thing that would prove it wrong — got wiped out. We’re standing on a floor we stared at as a ceiling for over a month.
So is Hayloo wrong? The 2026 crowd’s break-even now sits 7.11% below spot. Coinbase saw its heaviest net buying of the month on Wednesday, $88.8 million of real cash, and 5,823 coins came off exchanges the same day. Plenty of trading went through, but less than a dime of every dollar that changed hands in the funds was new money.
Long-term holders sold into every spike of the rally, a seventh straight week of realized losses at $327 million on the thirty-day average. The oldest Bitcoin money used the strength to leave the ship, which is one condition for a bear-market bottom to take shape. The other is enough buyers to scoop up the supply. Futures open interest crashed hard, dropping 34,315 coins, down 6.5%, while price ran. We hate to rain on anyone’s parade, but this rally showed up empty handed.
🟠 Spot changed hands, but nobody borrowed a dollar to buy this rally.
— Capital Flow Analyst (Priya Sandoval) · Fundamental Research Analyst (Charlotte Donovan)
Bitcoin keeps paying the majors – Hayloo’s Alt Tax Week 34

Hayloo’s Beta Desk. Beta is how far a coin travels when Bitcoin moves a dollar: above 1.00 it amplifies, below 1.00 it lags. The beta desk splits that by direction — what a coin catches on Bitcoin’s …
Hayloo’s Perp Book
Size and direction. Net short. Bitcoin: 233.900 coins long at $67,391.50 against 465.000 short at $68,749.00, for −231.100 net and an entry-net of −$16,205,413. Solana: 89,100 long at $86.82 against 125,100 short at $78.24, for −36,000 net and −$2,052,162 entry-net.
What the week cost. Our perp book gave back all unrealized hedging profit and is deeply green in spot. Thursday’s realized funding rate income was +$5,803.95, the four-week smoothed mean reads +$2,753.26 a day, which annualizes to +$1,004,939 and 15.70% of equity. Leveraged longs are paying us the best rate so far this cycle for the privilege of being on the right side of the longer trend all year.
Position versus thesis. The tape says the ceiling is a floor now and both recent-buyer rails are reclaimed. We see too many holders exiting into strength. No liquidity has been created and the driest months are still ahead of us. We hold our short position.
— Lead Trader (Jordi Federer)
🔴 Hayloo’s perp book is net short, paid its best carry of the cycle, to sit inside a range that has a glass floor.
Forward Thesis
Our case for holding on to our short positions is the profitability of weak hands, the lack of buyer conviction, the speculative liquidity cycle, and none of the three moved against us this week.
Our downside ladder needs an upgrade, but we won’t be shy adding to our short positions should 71K break on persisting on-chain weakness. With liquidity leaving financial markets, Bitcoin’s Realized Price at $52,685, sitting on top of the long-term-holder cost basis at $50,433, these are levels that are a hard sell after this week, but we’d consider them just as realistic as a break above 83K.
What would change our mind, each against its current value:
1. The next Michael Howell GLI print positive on the three-month rate with the nominal level rising alongside it. This week printed +2.6% with the level at $110.1 trillion, down from a revised $110.3 trillion.
2. A weekly close above $80,000 with volume joining the bid. Coinbase’s seven-day cumulative volume delta is positive; Binance’s is not.
3. Realized profit-loss sustained above 2.0 with confirmed accumulation. Now 1.11. It crossed 1.0 this week, halfway there.
Watchlist
Michael Howell’s next GLI print. Positive three-month with the level rising alters this trade. Positive three-month with the level falling again is a second base effect and changes nothing. The single highest-information number of the next month.
Bitcoin at $71,882 — the recent-buyer rail. Losing this level restores the capitulation read Hayloo’s trade runs on.
Bitcoin at $75,759 — the True Market Mean. The next wall, and the last one before we sleep with our eyes open...
Futures open interest at 494,739 coins. Falling through a rally is leverage leaving. If it turns up hard alongside price, the squeeze has become a position.
WTI’s weekly close, against a line near $71.92. Digital assets don’t recover easily on inflated energy.
The Team
Jordi Federer — Lead Trader. Owns the book and the publication. Sizing, staging, and every decision that moves capital.
Theodore Brennan — Chief Macro Strategist. Central-bank reaction functions, the dollar, and the rate path.
Julian Harlow — Global Liquidity Director. The liquidity engine, the collateral multiplier, and the transmission lag into price.
Margaux Lindqvist — Geopolitical Intelligence Officer. State behavior, escalation mechanics, and the tails that reprice commodities.
Marcus Vasquez — Hard Asset Strategist. Gold, the debasement basket, and the hard-money ratios.
Sienna Whitfield — Inflation & Real Asset Analyst. Energy, the inflation impulse, and the real-asset complex.
Priya Sandoval — Capital Flow Analyst. Fund flows, positioning, derivatives, and where the marginal dollar comes from.
Charlotte Donovan — Fundamental Research Analyst. On-chain cohorts, cost bases, and the structural read beneath the tape.
Lukas Marchetti — Technical Analyst. Market structure, moving-average regimes, and the levels that fire.
Disclaimer
The information is provided for information purposes only and on the basis that it will not be relied upon. No information contained herein constitutes a personal recommendation or investment advice.
The information (including any expressions of opinion or forecast) has been obtained from, or is based on, sources believed by the author to be reliable, but are not guaranteed as to their accuracy or completeness and should not be relied upon. The information is provided without obligation on the part of the author and on the understanding that any person who acts upon it or changes his investment position in reliance on it does so entirely at his own risk. The information does not constitute an offer to buy or sell or an invitation to make an offer to buy or sell any financial instrument.
Information is current only as at the date it is first posted and may no longer be true or complete when viewed by you. All information may be changed or amended without prior notice.
No representation, warranty or undertaking is given as to the accuracy or completeness of the information by the author and no liability is accepted by the author for the accuracy or completeness of such information. In no event will the author be liable to any person for any direct, indirect, special, or consequential damages arising out of any use of the information, including, without limitation, any lost profits.
You should be aware that the Internet is not a completely reliable transmission medium. The author does not accept any liability for any data transmission errors such as data loss or damage or alteration of any kind, including, but not limited to any direct, indirect or consequential damage, arising out of the use of the product or services referred to herein.
The materials provided here including text, photographs and other images, are protected by copyright and/or other intellectual property rights. All copyright (and any other intellectual property rights) in these materials is either owned by the author, or is used by the author under licence.